Effective Corporation Tax planning is not about a last-minute scramble for deductions; it’s a strategic framework for protecting assets, fuelling growth, and maximising director wealth.
- Proactive strategy prevents significant financial leakage and dramatically reduces the risk of costly HMRC investigations.
- The right structure for reinvestment, wealth extraction (salary vs. dividends), and asset holding is dynamic and must adapt to your business’s lifecycle and risk profile.
Recommendation: Implement a quarterly review process to assess your tax position against your strategic goals, not just your profit and loss statement.
For any director of a growing UK limited company, the year-end financial statement can feel like a paradox. Strong profits are a sign of success, yet they bring the unwelcome reality of a significant Corporation Tax bill. The default response is often a tactical scramble: claiming every allowable expense, reviewing the director’s loan account, and making a standard salary-dividend calculation. While these actions are necessary, they are fundamentally reactive. They treat tax as a problem to be minimised, rather than a strategic lever to be pulled.
The true cost of this reactive approach is not just the tax paid, but the opportunities lost. Cash trapped in the business depreciates with inflation, investment in innovation is delayed, and personal wealth extraction remains inefficient. For successful SMEs generating over £250,000, a fundamental shift in mindset is required. Tax optimisation should not be an annual event but an integrated part of your business strategy, designed to enhance growth, protect assets, and ensure full compliance with an increasingly vigilant HMRC.
This guide moves beyond the basics. We will dissect the critical strategic pillars of Corporation Tax planning for established, growing businesses. We will explore how to navigate complex areas like R&D tax credits without triggering alarms, determine the truly optimal wealth extraction mix for your specific circumstances, avoid the pitfalls that can invalidate valuable reliefs, and implement a robust treasury strategy to make your surplus cash work for you. It’s time to transform your approach from tax compliance to tax strategy.
This article provides a comprehensive framework for UK SME directors to rethink their approach to Corporation Tax. Below is a summary of the key strategic areas we will explore, designed to help you build a more resilient and efficient financial future for your company.
Summary: A Strategic Guide to Corporation Tax Optimisation
- Why Delaying Your Tax Strategy Costs UK Agencies £5,000 Annually?
- How to Claim R&D Tax Credits Without Triggering an HMRC Investigation?
- Salary or Dividends: Which Payout Structure Maximises Director Wealth Today?
- The Fatal Planning Mistake That Invalidates Your Business Relief Claims
- Overcoming Cash Traps: Structuring Your Profit Reinvestment for Maximum Efficiency
- Why Offering a 2% Discount is Often Cheaper Than Using an Invoice Factoring Facility?
- When to Move Excess Profits Into a Holding Company to Protect the Principal?
- Strategic Corporate Treasury: How to Protect Your Surplus UK Cash From Inflation?
Why Delaying Your Tax Strategy Costs UK Agencies £5,000 Annually?
The idea that tax planning is a year-end activity is one of the most expensive misconceptions in business. For a growing agency, treating tax as an afterthought is not just inefficient; it’s a direct drain on resources. The “cost” isn’t just a hypothetical figure; it materialises as missed deductions, late-filing penalties, and suboptimal use of capital allowances. Every quarter that passes without a strategic review represents a potential for profit leakage. When you consider that recent HMRC data reveals a £39.8 billion tax gap between expected and actual receipts, it’s clear that systemic inefficiencies and errors are widespread.
For a typical agency, this translates into tangible losses. A missed opportunity to maximise the Annual Investment Allowance on a new equipment purchase, failing to register for Corporation Tax within the three-month window, or neglecting to review allowable expenses on a regular basis are not minor oversights. They accumulate. An unclaimed expense of £500 here and a suboptimal capital allowance claim there can easily compound into thousands of pounds of unnecessary tax over a financial year. The £5,000 figure is a conservative estimate of the combined impact of these missed opportunities.
Adopting a proactive stance is the only effective countermeasure. This means moving from an annual review to a quarterly checkpoint. It involves a structured process to ensure that every strategic decision—from a new hire to a major client project—is considered through a tax lens. This isn’t about tax avoidance; it’s about strategic tax management that aligns with your growth ambitions and ensures you are operating with maximum financial efficiency.
Your Action Plan: 5 Critical Tax Planning Steps to Avoid £5,000+ Losses
- Register for Corporation Tax within 3 months of starting your limited company to avoid penalties.
- Maximise your Annual Investment Allowance claims up to £1 million for qualifying assets and equipment.
- Establish an EMI scheme while company valuation is low – opportunities once missed cannot be recovered.
- Time your accounting year-end to align with major product launches for optimal capital allowance claims.
- Review all allowable expenses quarterly to prevent missing deductions that accumulate to thousands annually.
Ultimately, a delayed strategy means you are leaving money on the table—money that could be reinvested into growth, used to reward your team, or strengthen your company’s financial resilience.
How to Claim R&D Tax Credits Without Triggering an HMRC Investigation?
Research & Development (R&D) tax credits represent one of the most powerful government incentives for innovative UK companies. However, the landscape has shifted dramatically. What was once a relatively straightforward process has become a high-scrutiny area for HMRC. With the confirmation that HMRC increased its R&D compliance checks to around 20% of claims in 2024, up from just 1% previously, the risk of an investigation has never been higher. A poorly prepared claim is no longer just a missed opportunity; it’s a significant business risk.
The core issue often lies in a misunderstanding of what constitutes “innovation” in HMRC’s eyes and, more critically, a failure in documentation. A successful claim hinges on demonstrating a “systematic, project-based approach to resolving scientific or technological uncertainty.” This requires more than simply having an innovative idea; it demands meticulous, contemporaneous records that prove the process. This includes project plans, technical specifications, test results, records of failures, and staff time-tracking allocated to specific R&D tasks. Without this evidence, even a genuinely innovative project can have its claim rejected.
This visual representation of a documentation system underscores the meticulous organisation required. The abstract textures of highlighted notes, paper clips, and diagrams represent the tangible evidence trail that HMRC inspectors now demand. This compliance-first mindset is the best defence against an inquiry.
Cautionary Tale: The High Cost of Ambiguous Innovation
The risk is not theoretical. A UK startup developing a novel database system provides a stark example. Despite believing their work was groundbreaking, they were instructed to repay £50,000 in previously granted tax credits. HMRC ruled that building upon existing systems did not meet the strict criteria for “innovation,” leading to the clawback and the rejection of a further £150,000 claim. This case highlights the critical importance of aligning your definition of R&D with HMRC’s and documenting every step of the journey.
Therefore, a successful R&D claim strategy in the current climate is twofold: first, rigorously assessing projects against HMRC’s strict definitions, and second, embedding a culture of detailed documentation from day one. This transforms the claim from a hopeful application into a verifiable statement of fact.
Salary or Dividends: Which Payout Structure Maximises Director Wealth Today?
The “salary versus dividends” debate is a cornerstone of tax planning for any UK limited company director. The conventional wisdom—taking a small salary up to the National Insurance threshold and the rest in dividends—has long been the default. However, for a growing, profitable company, this simplistic approach may no longer be optimal. The decision is now a dynamic balancing act between tax efficiency, personal financial needs, and the long-term health of the business.
A salary is a deductible expense for the company, reducing its Corporation Tax bill. However, it attracts both employee and employer National Insurance contributions (NICs) and is subject to Income Tax. Dividends, on the other hand, are paid from post-tax profits and are not subject to NICs, but have their own specific dividend tax rates. The optimal mix is not static; it depends on profit levels, cash flow stability, and the director’s personal circumstances, such as the need for a provable income for a mortgage application.
The following table provides a clear comparison of the key tax implications for the 2024/25 tax year, as detailed in a recent analysis of legal tax reduction methods. It serves as the factual basis for any strategic discussion.
| Payment Method | Tax Rate | National Insurance | Corporation Tax Impact | Best For |
|---|---|---|---|---|
| Salary up to £12,570 | 0% (Personal Allowance) | NI on income above £5,000 | Fully deductible | All directors (tax-free base) |
| Salary above £12,570 | 20-45% | Employee & Employer NI | Fully deductible | Mortgage applications |
| Dividends | 8.75% basic, 33.75% higher | None | Paid from post-tax profits | Stable high-profit companies |
| Pension Contributions | 0% (up to limits) | None | Fully deductible | Long-term tax efficiency |
While the table provides the raw data, the real value lies in its strategic application. A static model is insufficient for a dynamic business. A more sophisticated approach involves creating a flexible extraction strategy tailored to your company’s performance.
Your Action Plan: The Dynamic Salary/Dividend Strategy
- For stable businesses: Calculate the optimal mix with a £12,570 salary and plan regular quarterly dividends.
- For volatile cash flow: Set a lower fixed salary (e.g., £8,840) and time dividend payments flexibly after confirming profit levels.
- Integrate the Director’s Loan Account as an emergency buffer to avoid permanent salary increases during short-term cash needs.
- Review profit consistency quarterly and be prepared to adjust the dividend/salary mix accordingly.
- Document your lifestyle compatibility needs annually, balancing the priority between mortgage applications (favouring salary) and pure tax efficiency (favouring dividends).
Ultimately, the most effective strategy moves beyond a one-size-fits-all formula. It requires a quarterly assessment of business profitability and personal requirements to ensure your wealth extraction method remains perfectly aligned with both your company’s health and your financial goals.
The Fatal Planning Mistake That Invalidates Your Business Relief Claims
For many business owners, their company represents their life’s work and a significant part of their estate. Business Relief (BR) is a crucial form of Inheritance Tax relief designed to allow family businesses to be passed down without being broken up to pay taxes. However, a common and often fatal planning mistake can inadvertently render a company ineligible, with devastating financial consequences for the next generation. This mistake is the gradual and unmanaged accumulation of non-trading (investment) assets within the main trading company.
HMRC’s rules are clear: to qualify for BR, a company must be “wholly or mainly” a trading entity. While there’s no strict statutory definition of “mainly,” it is generally accepted that trading activities should outweigh non-trading activities across multiple metrics (turnover, profit, asset value, director time). The trap is that a successful, cash-generative trading business often accumulates surplus cash, which is then used to acquire investment assets like a rental property or a stock portfolio. Over time, the value and income from these investments can grow to a point where they tip the balance, and HMRC deems the company to be primarily an investment entity.
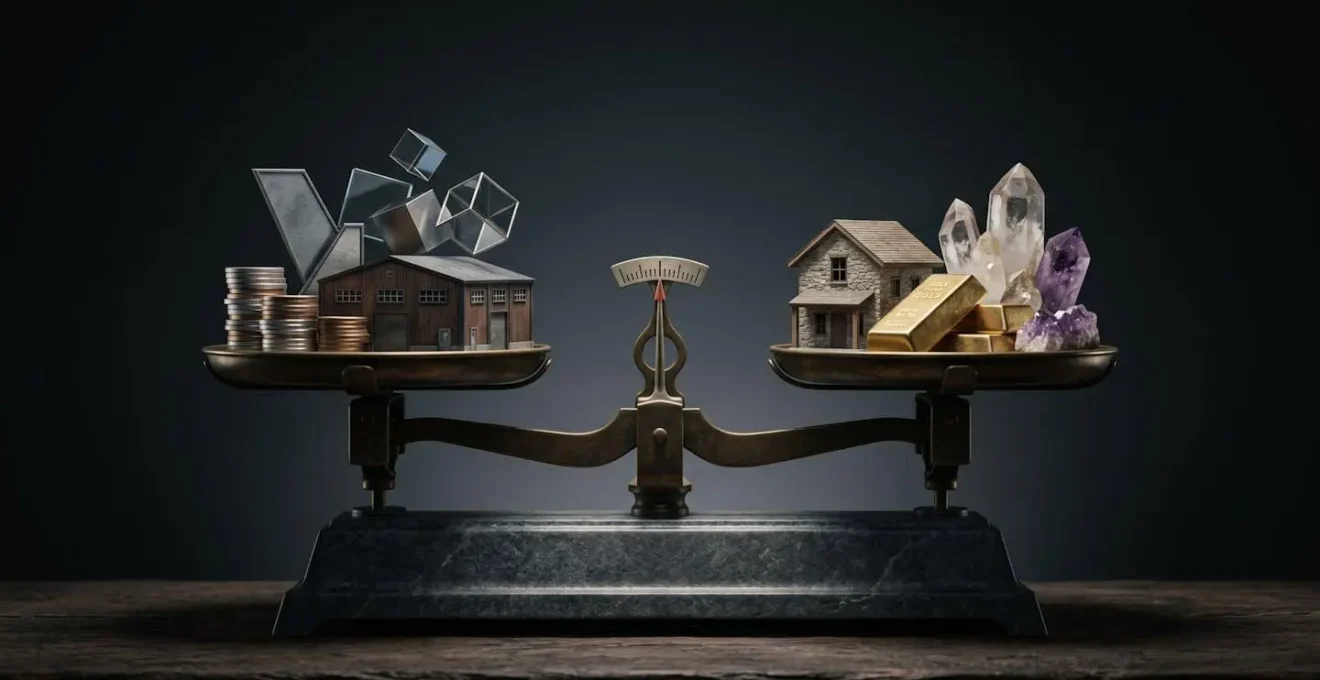
The image of the scales represents this precarious equilibrium. On one side, the symbols of active trade; on the other, static investment assets. When the investment side becomes too heavy, the company’s trading status is jeopardised, and the entitlement to Business Relief is lost entirely. This is not a partial reduction; it is a total invalidation of the claim.
How Success Can Invalidate Your Legacy
Consider a successful consulting firm that, over years of profitability, purchases its office building and an additional rental property. As the property values and rental income grow, they can begin to represent a significant portion of the company’s balance sheet and profits. Without a holding company structure to legally separate the trading activities from these investment assets, the firm risks failing the “wholly or mainly” trading test. Upon the shareholder’s death, what was assumed to be a 100% tax-free asset could suddenly face a 40% Inheritance Tax charge, simply due to a lack of structural planning.
Your Action Plan: The Business Relief Protection Checklist
- Monitor non-trading assets quarterly. Trigger a strategic review when they approach or exceed 20% of the company’s balance sheet value.
- Document the ’wholly or mainly’ trading test using multiple metrics (e.g., turnover, asset value, director time), not just relying on a simple 51% rule.
- Review all shareholder agreements and binding contracts for any clauses that could inadvertently convert shares into a right to receive cash.
- Proactively separate significant investment assets into a distinct holding company structure before they accumulate and contaminate the trading entity.
- Track and document director time allocation between trading activities and the management of any investment activities on a monthly basis.
Protecting your Business Relief eligibility requires constant vigilance and, most importantly, the right corporate structure. The fatal mistake is not making investments, but failing to house them correctly.
Overcoming Cash Traps: Structuring Your Profit Reinvestment for Maximum Efficiency
For a successful SME, generating profit is only half the battle. The other half is deploying that profit effectively. Leaving large sums of cash sitting in a current account is a common “cash trap”—it’s an unproductive asset that is actively losing value to inflation and represents a missed opportunity for growth or tax-efficient extraction. A strategic approach to profit reinvestment is essential for maximising the velocity and efficiency of your capital. This means having a clear, tiered structure for your surplus cash, moving beyond a simple “savings” mindset.
The first priority is liquidity, ensuring you have enough cash to cover 6-18 months of operating expenses. Beyond this, however, the strategy should diverge based on risk and time horizon. One of the most powerful and often underutilised tools for tax-efficient extraction is the director’s pension. Company contributions to a director’s pension are typically fully deductible against Corporation Tax, and there is no personal tax liability for the director. With current UK pension rules allowing contributions up to a £60,000 annual allowance (with potential to carry forward unused allowances), this represents a significant opportunity to move profits out of the company in a highly efficient manner.
Beyond personal extraction, structuring reinvestment requires discipline. Instead of ad-hoc spending, a formal framework helps to allocate capital to its most productive use. This could involve creating a “venture arm” within the business, with a specific budget allocated to new growth projects that have clear ROI targets. This imposes the same rigour on internal investment as you would expect from an external investor. For longer-term strategic goals, such as acquiring commercial property, a Self-Invested Personal Pension (SIPP) or Small Self-Administered Scheme (SSAS) can be used to purchase a property that is then leased back to the trading company, creating a virtuous cycle of rent payments that build your pension pot.
Your Action Plan: The Tiered Profit Reinvestment Strategy
- Tier 1 (Liquidity): Allocate 0-6 months of operating expenses to an instant-access, high-interest business savings account for immediate needs.
- Tier 2 (Working Capital): Place funds covering 6-18 months of expenses into short-term Gilts or Money Market Funds to achieve a better yield with minimal risk.
- Tier 3 (Growth Capital): Structure any surplus beyond 18 months as a “venture arm” with specific project budgets, milestones, and ROI targets to fuel strategic growth.
- Tier 4 (Efficient Extraction): Maximise director pension contributions (up to the £60k annual allowance) as a primary method for tax-efficient profit extraction.
- Tier 5 (Strategic Assets): Consider using a SIPP/SSAS to acquire commercial property for the business, turning a major expense (rent) into an investment.
By moving from a passive “cash trap” to an active, tiered reinvestment strategy, you transform idle profit into a powerful engine for both corporate growth and personal wealth accumulation.
Why Offering a 2% Discount is Often Cheaper Than Using an Invoice Factoring Facility?
Cash flow, not just profit, is the lifeblood of any growing business. When clients pay on 30, 60, or even 90-day terms, it can create a significant cash flow gap. A common solution is invoice factoring, where a third-party company buys your invoices at a discount to provide immediate cash. While this solves the immediate liquidity problem, its true cost is often misunderstood and can be substantially higher than the headline rate suggests. A more strategic, and often cheaper, alternative can be to offer a simple early payment discount directly to your clients.
The key is to analyse the “true annual rate.” A factoring company might advertise a rate of 1-3%, but this is typically a monthly charge. An annualised rate, once service fees and other charges are included, can easily reach 15-30% or more. In contrast, offering a 2% discount for payment within 10 days instead of 30 is a one-time cost. While it seems like you are giving away 2% of your revenue, you are gaining access to your cash 20 days earlier. More importantly, it strengthens your relationship with your best clients, positioning the discount as a partnership benefit rather than a sign of financial strain, which can sometimes be the perception when a factoring company gets involved.
A recent comparative analysis of financing options highlights the stark difference in the total cost of capital. This data provides a clear financial rationale for carefully considering your approach to accelerating cash flow.
| Cost Factor | 2% Early Payment Discount | Invoice Factoring |
|---|---|---|
| Headline Rate | 2% one-time | 1-3% monthly |
| True Annual Rate | 2% (if paid 30 days early) | 15-30% including fees |
| Service Fees | None | 0.25-0.5% of turnover |
| Minimum Usage | Selective application | Often whole ledger required |
| Client Relationship | Strengthens (partnership benefit) | Potential strain (suggests instability) |
| Management Time | Minimal | Significant ongoing |
A Hybrid Approach to Optimise Cash Flow
A UK digital agency successfully implemented a targeted discounting strategy. They offered early payment discounts exclusively to their top 20% of clients—those who were reliable, high-volume, and had a strong existing relationship. For smaller or less predictable clients, they maintained their standard payment terms. This hybrid approach improved their overall cash flow by 35% while completely avoiding the high effective annual rates and administrative burden associated with a blanket factoring arrangement. It allowed them to reap the benefits of early payment without incurring the high costs or potential client relationship damage of factoring.
Factoring has its place, particularly in distressed situations, but for a healthy, growing business, a strategic and selective early payment discount programme is a more cost-effective and relationship-friendly tool for managing cash flow.
When to Move Excess Profits Into a Holding Company to Protect the Principal?
“A holding company structure enables tax-efficient profit distribution through dividends, potentially reducing overall tax liability.”
– Tax Cloud UK, 11 Legal Ways to Reduce Corporation Tax 2024
As a business matures and becomes consistently profitable, it starts to accumulate a significant asset: retained profits. While this is a sign of success, it also introduces risk. These profits, held within the trading company (“OpCo”), are exposed to all the operational risks of the business—creditors, litigation, and market downturns. A holding company (“HoldCo”) structure is a primary mechanism for protecting this accumulated wealth. The critical question for directors is not *if*, but *when* to implement this structure. The answer lies in monitoring specific financial triggers.
A HoldCo is a separate limited company set up to own the shares of your trading OpCo. Its primary function is to receive dividends from the OpCo and hold them in a legally separate and protected environment. This process, known as “upstreaming,” moves the cash away from operational risk. The key benefit is asset protection. If the trading company were to fail, the cash and assets held in the HoldCo would generally be shielded from the OpCo’s creditors.
This structure also provides significant flexibility for future investment. The HoldCo can become a Family Investment Company, using the accumulated profits to invest in sustainable wealth strategies, or even to fund new business ventures, all without contaminating the trading status of the original operating company. This is crucial for preserving eligibility for reliefs like Business Relief, as discussed earlier. Making the move to a HoldCo structure is a strategic decision that should be guided by clear indicators within your business’s financial health.
Your Action Plan: Holding Company Implementation Triggers
- Trigger 1 (Asset Mix): Initiate a HoldCo review when non-trading assets (like property or investments) held within the operating company approach or exceed 20% of its balance sheet.
- Trigger 2 (Cash Reserves): Consider implementation when retained profits within the operating company surpass 12-18 months of your total operating expenses.
- Process (Shareholders): Ensure the dividend waiver process is structured correctly and documented meticulously if multiple shareholders exist with different interests.
- Process (Documentation): Formally document the board’s intention to separate and protect family wealth from the inherent risks of the trading operation.
- Process (Investment): Use the HoldCo as the designated vehicle for all future non-trading activities, such as property acquisition or diverse market investments, to maintain a “clean” operating company.
By identifying these triggers in advance, you can transition from a single-entity risk model to a more resilient two-tier structure at the optimal moment, securing the wealth you’ve worked hard to build.
Key takeaways
- A proactive, quarterly tax review is a strategic imperative, not a year-end administrative task; it prevents financial leakage and aligns tax with business goals.
- Meticulous, contemporaneous documentation is your single greatest defence against HMRC scrutiny, particularly for high-risk areas like R&D tax credits.
- Corporate structure is a critical tool for risk management; separating trading activities from investment assets via a holding company is essential for long-term asset protection.
Strategic Corporate Treasury: How to Protect Your Surplus UK Cash From Inflation?
Once you have successfully generated profits and protected them from operational risk, the final strategic challenge is to protect their value. In an inflationary environment, cash held in a low-interest business account is a depreciating asset. A strategic corporate treasury function, even for an SME, involves actively managing this surplus cash to preserve its purchasing power and generate a low-risk return. This is not about speculative investment; it is about prudent and efficient cash management.
The approach should be tiered, balancing the need for liquidity with the goal of achieving a better return than a standard bank account. For cash needed within the next 6-18 months, there are several low-risk, liquid options available to UK companies. Short-term UK Government Bonds (Gilts) are a primary choice, as they offer a competitive yield and any capital gains are typically exempt from Corporation Tax. Money Market Funds (MMFs) are another excellent option, providing yields that closely track the Bank of England base rate with near-instant liquidity.
The key is to create a formal cash management policy that defines which types of investments are permissible and sets limits for each. This provides a framework for making decisions that are consistent with the company’s risk appetite. A comprehensive review of investment options for corporate cash shows the clear yield advantages of moving beyond a simple savings account.
| Investment Type | Risk Level | Typical Yield (2024) | Liquidity | HMRC Treatment |
|---|---|---|---|---|
| Business Savings Account | Very Low | 3-5% | Instant | Interest taxable |
| UK Gilts (Short-term) | Low | 4-5% | 1-3 months | Capital gains exempt |
| Money Market Funds | Low | 4.5-5.5% | T+1 days | Income taxable |
| Corporate Bond ETFs | Low-Medium | 5-7% | T+2 days | Income and gains taxable |
| Fixed-Term Deposits | Very Low | 4-6% | Fixed term | Interest taxable |
Your Action Plan: The Three-Tier Corporate Cash Management Strategy
- Tier 1 (Liquidity: 0-6 months expenses): Keep this portion in a high-interest, instant-access business savings account for immediate operational needs.
- Tier 2 (Core Surplus: 6-18 months expenses): Allocate this to short-term UK Gilts or Money Market Funds to achieve a better yield while maintaining high liquidity and low risk.
- Tier 3 (Strategic Surplus: >18 months): For cash not needed in the medium term, consider strategic reinvestment back into the business or a formal transfer to a holding company for long-term investment.
- Currency Hedging: If your business has significant import costs, use forward contracts to lock in exchange rates and protect against GBP weakness, stabilising your cost base.
- Quarterly Review: Review your cash allocations every quarter, adjusting based on updated cash flow projections and prevailing interest rates.
By implementing a structured, multi-tier cash management strategy, you transform your corporate treasury from a passive cost centre into an active function that preserves capital and contributes to the company’s overall financial health. To implement a robust corporate treasury and tax optimisation strategy, the next logical step is a bespoke assessment of your company’s unique financial landscape.